What Mine Subsidence Is
Mine subsidence is damage to a structure from the caving in of underground mines. Ohio's insurance rules define it as loss caused by the collapse or the lateral or vertical movement of structures resulting from the caving in of underground mines, including coal, clay, limestone, and salt mines. When the tunnels and voids left by old mining give way, the ground above can sink or shift, and what stands on it moves too.
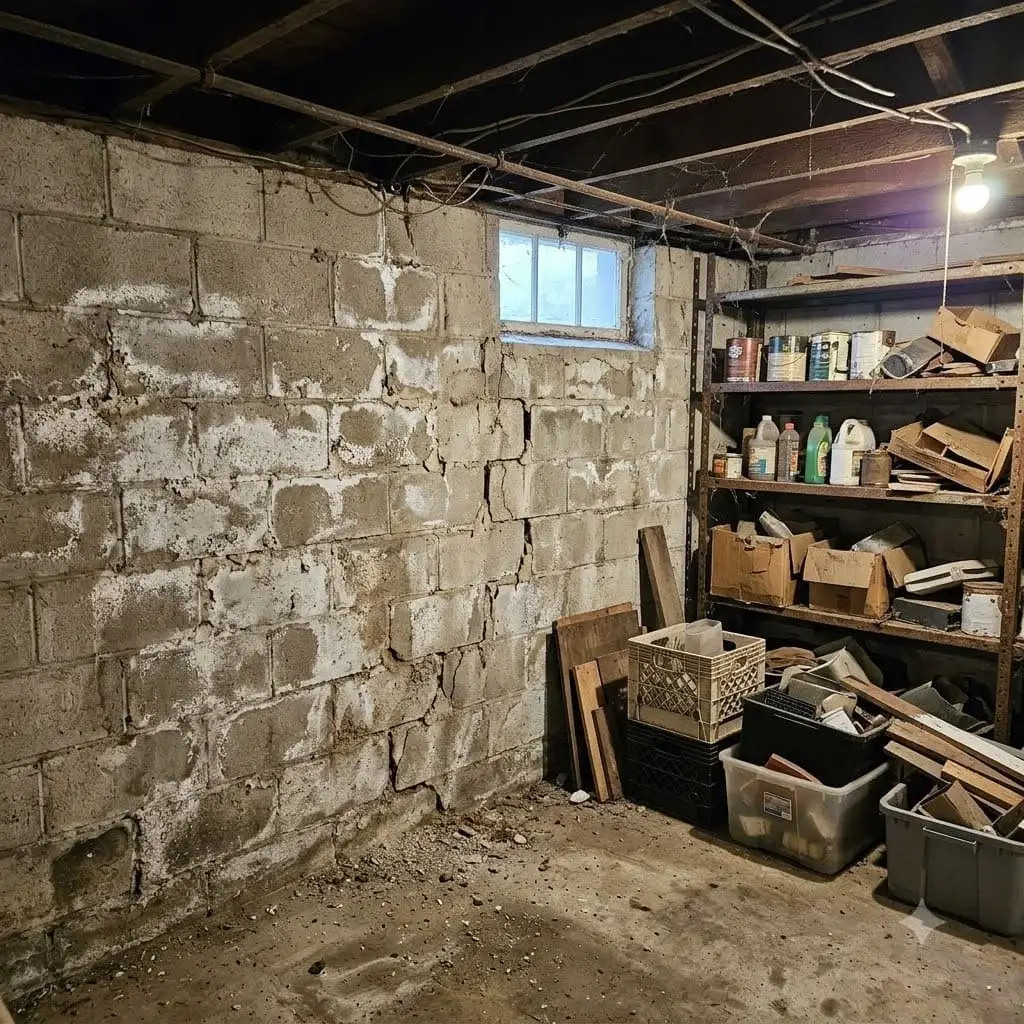
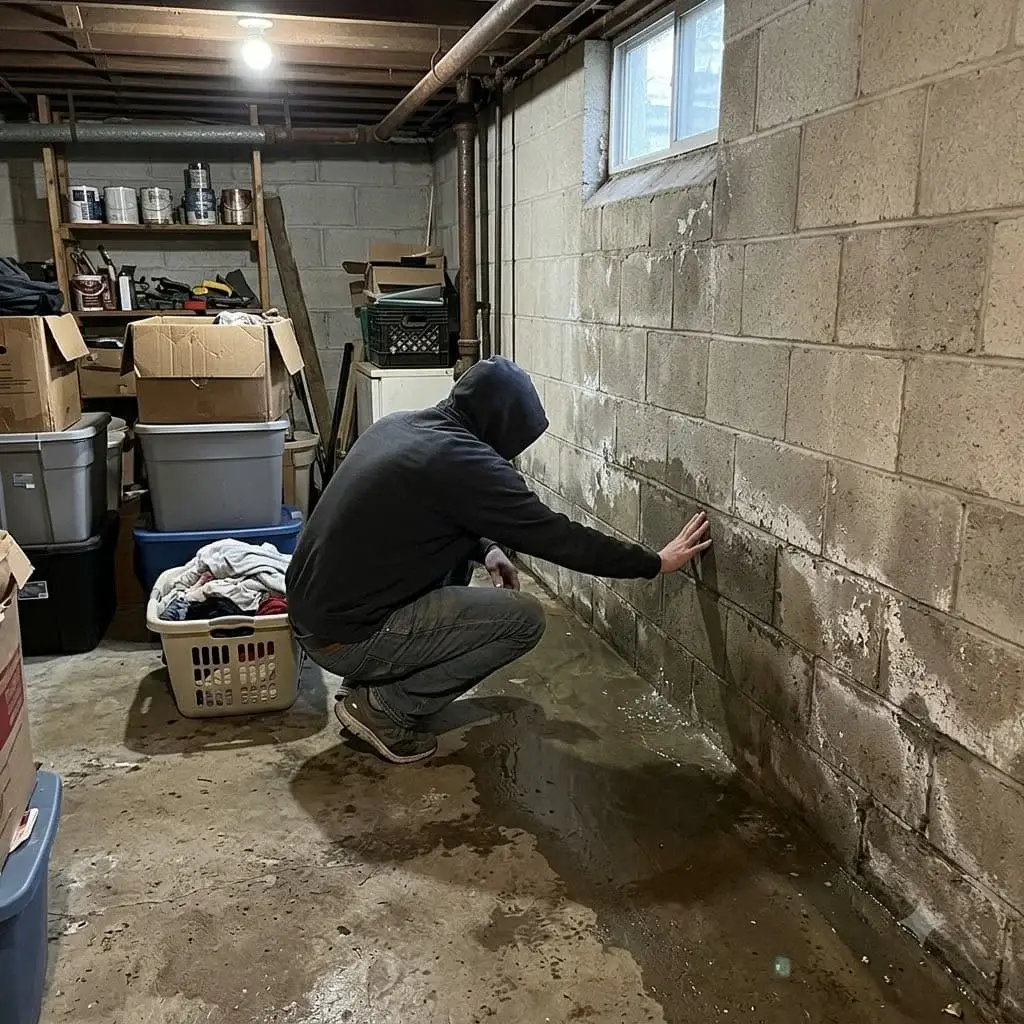
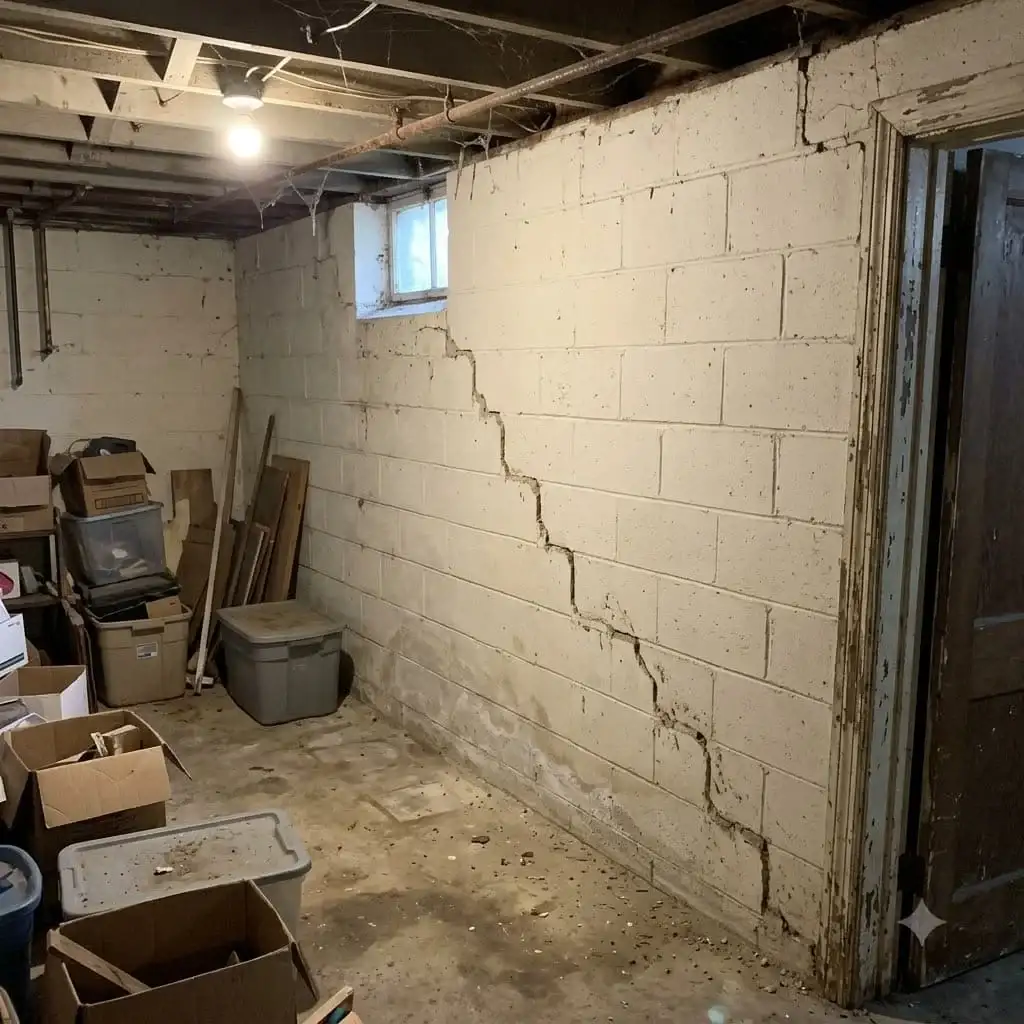
Damage looks like cracks in walls and foundations, doors and windows that stick, and floors that go uneven. Those signs overlap with ordinary water and settlement damage, which makes them easy to misread.
Why Trumbull County Policies Include It
Ohio Revised Code section 3929.56 lists 26 counties where insurers must include mine subsidence coverage, and Trumbull is on that list, along with neighbors Mahoning and Columbiana. An insurer that offers basic property and homeowners insurance on a structure in those counties must include coverage provided through the Ohio Mine Subsidence Insurance Underwriting Association in each policy it issues, delivers, or renews. The statute contains no opt-out for those counties.
The Terms
Ohio's plan of operation sets the main terms for the dwelling on your homeowners policy.
- The limit. Coverage for direct loss from mine subsidence can't exceed the dwelling coverage on your homeowners policy or $300,000, whichever is less.
- The deductible. The deductible falls between $250 and $500.
- The premium. The plan caps the annual premium at $5 in the mandated counties, and at $20 in counties where coverage is optional.
- Eligibility. A member insurer can refuse coverage on a structure that has unrepaired subsidence damage or subsidence damage in progress.
Your own policy sets the exact terms, so check your declarations page.
What It Doesn't Cover
This coverage addresses a single cause. Ohio's rules name several things that don't count as mine subsidence, including earthquakes, landslides, volcanic eruptions, and the collapse of strip mines, storm and sewer drains, and rapid transit tunnels. It also doesn't address water in a basement. Groundwater, seepage, and flooding are separate matters, and most homeowners policies exclude them on their own terms.
How to Find Out Where You Stand
Start with your insurance agent, since the coverage is part of the policy you already carry in Trumbull County. Ask whether it appears on your declarations page and what the limit and deductible are. The Ohio Department of Natural Resources publishes a statewide map of abandoned underground mines showing where old workings sit. If you see cracks or movement and can't tell what is behind them, an inspection can separate water pressure and soil from ground movement.
How This Relates to a Wet or Cracked Basement
Subsidence and water damage look alike but have different causes. A bowing wall or cracked foundation in a Warren basement most often comes from saturated clay-rich soil and water pressure, which we address with waterproofing and wall repair. Ground movement from old mines is a separate cause, and it is a matter for your insurer, not a waterproofing contractor. When we inspect a basement with cracks or movement, we go through what applies so you can contact your insurer before the problem grows. Our guide to older Warren homes and basement moisture covers the water side of the story.
Frequently Asked Questions
Does homeowners insurance cover mine subsidence in Ohio?
Ohio requires mine subsidence coverage in homeowners policies in 26 counties, including Trumbull, Mahoning, and Columbiana. Insurers provide it through the Ohio Mine Subsidence Insurance Underwriting Association. In the counties where coverage is optional, insurers offer it and county commissioners can choose to require it. Check your declarations page, or ask your agent to confirm the coverage and its limits on your policy.
What are the limit and deductible for Ohio mine subsidence coverage?
The limit is the dwelling coverage on your homeowners policy or $300,000, whichever is less. The deductible must fall between $250 and $500. Insurers can sell coverage above $300,000 on their own. Because the dwelling limit on your policy sets the real cap, read your policy and ask your agent how the two numbers apply to your home.
Does mine subsidence insurance cover basement water?
It doesn't. Mine subsidence coverage applies to loss from the caving in of underground mines. Groundwater seepage, flooding after heavy rain, and sewer backup are separate causes, and most homeowners policies exclude them unless you add specific coverage. A wet Warren basement comes from saturated soil far more often than from mine movement.
Is mine subsidence the same as a sinking foundation?
They can look the same but have different causes. Subsidence is ground movement from collapsing underground mines, while settling and wall bowing in Warren usually come from soil conditions and water pressure. Both show up as cracks, sticking doors, and uneven floors. The difference matters because subsidence may fall under the coverage in your policy, while water-driven movement is a waterproofing and repair matter.
Can an insurer refuse mine subsidence coverage?
A member insurer can refuse coverage on a structure that has unrepaired subsidence damage or damage in progress. For a home with no existing subsidence damage in a mandated county, the coverage is included by law. If you've found cracks and aren't sure why, get the cause identified before you change or renew a policy, and ask your agent how your insurer handles it.